Business
How To Launch Your Own Car Decal Business in 2025

Ever spot a bold sticker on a car and think, “I could make that”? 2025 is the perfect year to turn that thought into a business. Drivers crave fresh ways to personalize their rides, and decals are cheap to make yet sell well. All you need is a clear plan, basic gear, and creativity to start earning on your hobby.
Map Out Your Vision
Begin with a focused idea. Will you feature witty sayings, team pride, pet silhouettes, or all of the above? Write down the styles you like and sketch samples on paper or a tablet. Show them to relatives, friends, or online groups and note which designs spark excitement.
Next, set income targets you can measure, such as selling fifty decals a week at ten dollars each. Simple math tells you whether the goal pays your bills. Finish by choosing a catchy name, checking the web address, and grabbing matching social pages.
Gather the Right Tools
You do not need a factory, but you do need reliable gear. A small desktop cutting machine slices vinyl cleanly and costs far less than industrial models; watch for sales to save more. Stock basic vinyl rolls in black, white, and three bright colors so you can fill common requests right away.
Add transfer tape, a squeegee, and a sharp craft knife for trimming edges. A laptop plus free design software lets you create or tweak images without extra fees. Keep every receipt because start-up costs may lower your taxes.
Set Up Shop and Sell
Open a simple online store first. Many platforms let you post ten products for free, so pick one and upload bright photos taken in daylight. Always show a decal on an actual vehicle, not just a plain background, so shoppers grasp the scale.
Keep descriptions short and clear, list color choices, and state processing time honestly. Offer free shipping on orders over a set amount; the perk often boosts cart size enough to cover the cost. If you enjoy people, rent a booth at weekend markets or local car meets, too.
Spread the Word and Grow
Promotion does not have to be expensive. Ask every happy buyer to post a photo and tag your page; real pictures beat paid ads. Shoot quick behind-the-scenes clips that show a decal from design to final press and add upbeat music. Contact local auto clubs and offer a small discount for group orders, which can snowball into steady work.
Be present at charity cruises or school fundraisers and donate a few stickers for prizes. One excited driver showing off custom car decals to friends will spread your name fast and far.
Conclusion
Starting a car decal business in 2025 is less about luck and more about clear steps. Plan your niche, stock smart tools, showcase your work, and keep the conversation going. Stay patient, refine your designs, and treat every customer like a partner. Follow this path, and your first roll of vinyl could mark the beginning of a thriving, long-lasting brand.

You’ve found a house that seems perfect. The kitchen looks beautiful, the bedrooms are spacious, and you can already imagine moving in. There’s just one problem: you’re not sure whether the asking price is reasonable or whether you’re about to pay more than the property is worth.
Property prices can be difficult to judge, especially when homes in the same neighbourhood sell for surprisingly different amounts. Sellers naturally want the highest possible price, while buyers need to understand what they’re actually getting for their money.
The good news is that you don’t need to be a property expert to make a more informed decision. Comparing recent sales, examining the property’s condition and understanding local demand can help you assess its value. Some buyers also seek professional guidance, such as a buyers agent Sydney, to help evaluate properties and negotiate with sellers.
Compare Recently Sold Properties
One of the most reliable ways to assess a property’s asking price is to examine what similar homes have recently sold for.
Advertised prices aren’t always useful because they reflect what sellers hope to achieve rather than what buyers ultimately pay.
Look for completed sales involving properties with comparable characteristics.
Consider factors such as:
- Number of bedrooms and bathrooms.
- Internal living space and land size.
- Property age and overall condition.
- Parking availability and outdoor areas.
- Proximity to schools, shops and transport.
- Recent renovations or additional features.
Try to compare several properties rather than relying on a single sale.
If similar homes consistently sell for less, the asking price may deserve closer examination.
Look Beyond the Fresh Paint
A beautifully presented property can make a strong first impression, but cosmetic improvements don’t necessarily increase its value by the amount they cost.
Fresh paint, stylish furniture and new flooring can make a home look appealing while hiding older fixtures or maintenance issues.
During inspections, look carefully for signs of moisture, cracking, uneven flooring and damaged fittings.
Ask about the age of major systems, including heating, cooling, roofing and plumbing.
A professional property inspection can help identify problems that aren’t immediately obvious.
If significant repairs are required, factor those expenses into your assessment before making an offer.
Consider the Location Carefully
Two similar houses can have very different values because of their surroundings.
A property near desirable schools, public transport or convenient amenities may attract stronger demand than one in a less accessible location.
However, location isn’t simply about distance to shops or the city centre.
Traffic noise, neighbouring buildings, parking conditions and nearby developments can also influence a property’s appeal.
Visit the neighbourhood at different times of day.
A quiet street during a weekday inspection might experience heavy traffic during school drop-off or evening commuting periods.
Understanding these practical details can help you judge whether the location justifies the asking price.
Understand the Current Market Conditions
Property values are influenced by supply and demand.
When many buyers compete for relatively few homes, sellers may have greater negotiating power.
In slower markets, buyers may have more opportunities to negotiate or request favourable conditions.
Look at how long comparable properties remain listed and whether sellers are reducing their asking prices.
It’s also worth considering the number of similar homes currently available.
However, avoid assuming that every property follows the broader market. Homes with unusual features or desirable locations may attract different levels of interest.
Calculate the True Cost of Ownership
The purchase price is only one part of the financial commitment.
Before deciding whether a property represents good value, consider the additional expenses involved.
Depending on your location and circumstances, these may include mortgage fees, insurance, property taxes, inspections and legal costs.
Ongoing maintenance should also influence your decision.
An older home with an attractive asking price might require substantial repairs during the first few years of ownership.
Estimate these potential costs and consider whether the property still fits comfortably within your budget.
Don’t Let Competition Push You Beyond Your Limit
It’s easy to become emotionally attached to a property, particularly when other buyers are interested.
However, competition doesn’t automatically mean the home is worth more.
Before making an offer, establish a maximum price based on comparable sales, property condition and your financial circumstances.
Keep that figure separate from the seller’s expectations.
If negotiations exceed your limit, be prepared to walk away.
There will usually be other opportunities, and avoiding an unaffordable purchase can be more important than winning a competitive negotiation.
Make Your Decision With Confidence
Determining whether a property is worth its asking price involves more than looking at photographs or listening to a selling agent’s recommendations.
Recent sales, building condition, location and ownership costs all contribute to the bigger picture.
Take time to investigate these factors and seek independent professional advice where appropriate.
A property doesn’t need to be the cheapest available to represent good value. It needs to offer the right combination of features, condition and affordability for your circumstances.
By approaching the decision with research rather than emotion, you can make an offer that reflects what the property is genuinely worth to you.
A framing sub wraps up a mixed-use building in year one, cashes the final check, and moves on to the next job. Eight years later, a tenant trips on a slab that cracked where the sub’s crew tied two pours together, breaks a hip, and sues the owner and the general.
The general tenders the claim back to the sub as an additional insured. The sub’s broker digs out the old certificate, sees the only endorsement on file was a CG 20 10, and figures out the policy that was supposed to protect them stopped responding the day the work ended.
Most completed-operations fights start right there, in the space between what a contractor thinks they bought and what the policy actually does when the phone rings. By then the project is closed, the paperwork is cold, and the people who negotiated the contract have moved on.
Stage One: The Contract Promises More Than the Endorsement Delivers
Most construction contracts require the contractor to name the owner, developer, and upstream contractor as additional insureds. The language usually reads something like “for ongoing and completed operations.” Fine on paper, but here’s the catch. The standard ongoing-operations endorsement, CG 20 10, was narrowed after 1985 so it stops responding once the work is finished. If that’s the only endorsement attached to the policy, the completed-operations half of the contract promise has nothing behind it.
Covering both halves generally takes two separate endorsements, as the Amwins client advisory on additional insured forms lays out: a CG 20 10 for the construction phase and a CG 20 37 for the years after the ribbon is cut. Plenty of contracts assume both are in place. Plenty of policies carry only one. A thoughtful business insurance program builds this handoff in, pairing the right additional insured forms with completed-operations limits that will still be meaningful a decade out.
Stage Two: The Latent Defect Shows Up
Water intrusion. Foundation movement. Failed waterproofing, EIFS problems, slab cracks.
Construction defects can also stem from decisions made long before a project is finished. As Emoovio explains in its article on construction preparation mistakes, rushed preparation can lead to premature failures that only become apparent months or years later.
These rarely surface in year one. Claims typically aren’t reported for a number of years, often up to ten, after a home is completed. Commercial projects follow a similar curve. By the time the damage is visible, the original crew is on different jobs and the insurance file is buried in deep storage.
State statutes of repose cap how far back a plaintiff can reach, but the ceilings are generous and they vary widely by jurisdiction. The practical window a contractor should plan to defend against runs well past a decade in many places.
Stage Three: The Tender Lands on the Wrong Policy Year
When the suit arrives, the general or the owner tenders it to every sub whose scope touched the alleged defect. Whether that tender gets accepted depends on four things, and none of them are what the current broker is quoting:
- The endorsement in force then. The policy that responds is the one on the risk when the property damage happened, not the policy in force today. A CG 20 10 on that old policy will usually fail to pick up a completed-operations claim.
- The schedule of insureds. Older endorsements often required the additional insured to be named specifically. If the upstream party isn’t on the schedule, or isn’t captured by a blanket clause tied to a written contract, the tender gets denied.
- The completed-operations limit. Products-completed operations usually has its own aggregate. If prior claims already chewed through it, there may be little or nothing left for this one.
- The surviving paperwork. No contract on file, no certificate, no endorsement copy, no coverage argument. Document retention for a contractor is a coverage issue, not a records issue.
Stage Four: Close the Loop Before the Next Project Starts
The fix is boring, and it works. Read the insurance exhibit in every contract before signing and match the endorsements on the policy to what the contract actually requires. If the contract calls for completed-operations additional insured status, confirm a CG 20 37 (or equivalent) is attached, not a CG 20 10 by itself.
Ask the carrier for a specimen copy of the endorsement, not a certificate. A certificate is a summary, not coverage. A few habits save real money later:
- Keep a project-by-project file. Store the signed contract, the certificate, and the actual endorsement forms together, by project, for at least the length of the longest statute of repose you work under.
- Watch the completed-operations limit. Buy it high enough that one bad project doesn’t exhaust it for everything else, and track erosion as claims come in.
- Keep tail coverage alive. If you change carriers, retire, or sell the business, confirm how completed-operations claims from prior years will be defended. Leave that question open and personal assets start getting discussed.
- Push back on blanket language that doesn’t match. If a contract demands coverage your policy doesn’t grant, flag it before signing, not after a tender.
Contractors who get surprised by a tender ten years out usually did the work well. What tripped them was an endorsement that expired the moment the job did.
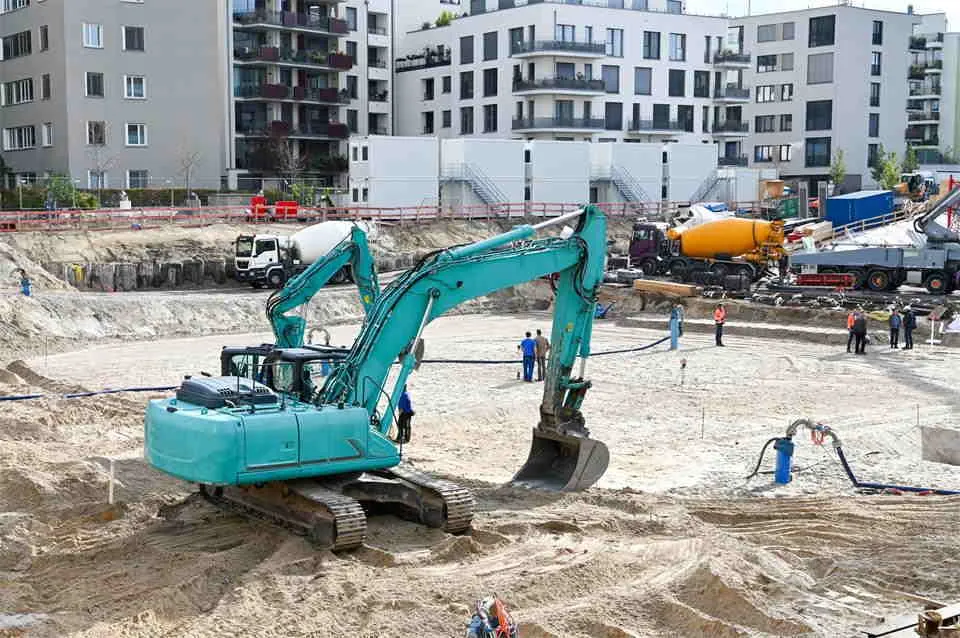
Disagreements over substantial completion can quickly turn into construction payment disputes when owners and contractors have different expectations about what it means for a project to be finished. A contractor may consider the work substantially complete once the building can be used for its intended purpose, while an owner may argue that outstanding repairs, unfinished installations, or other punch list items justify withholding payment.
These disputes often center on the punch list, which documents the remaining work needed before a project is considered fully complete. What one party views as minor cosmetic fixes, the other may see as significant deficiencies that prevent final acceptance.
Understanding how substantial completion is defined, documented, and addressed in the construction contract can help both sides protect their interests and avoid costly delays.
The Contractor’s View Versus the Owner’s View of the Same List
For the contractor, substantial completion is a status. The building can be used for its intended purpose, the punch list is the short remainder, and payment should flow. For the owner, substantial completion is a concession, and signing it off means handing over the one piece of real pressure still available in the project: the money sitting in retainage.
When a dispute is heading toward counsel, an experienced construction attorney will read the contract’s completion clause first, because the drafting choice usually dictates the shape of the negotiation that follows.
Both sides are reading the same list of items. They are not reading it the same way. A missing closet shelf and a dead rooftop exhaust fan may sit on the same page of the same punch list, but one is a finish item and the other may be the reason the certificate of occupancy is being held. Lumping them together is how disputes start. Separating them is how they get resolved.
Occupancy Is Not the Same Thing as Acceptance
Owners move in before they sign. That’s the awkward middle ground where most of these fights live. The owner is operating in the space, storing inventory, running tenants, taking reservations, while refusing to issue the certificate that would start the warranty clock and release retainage.
Contractors argue, with some force, that beneficial use is the whole point of the doctrine. If the owner is using the building for its intended purpose, the remaining items belong on a punch list rather than in a payment freeze.
Owners counter that use under protest isn’t acceptance, especially when they moved in because a tenant was waiting or a season was closing. The contract language usually decides which argument wins, and most contracts are vaguer on this point than either party remembers.
Define the Triggering Event in the Contract, Not After the Fight Starts
The cleanest projects name the exact event that establishes substantial completion before a shovel hits the ground. The messiest ones leave it to be argued later. There are only a handful of candidates worth naming:
- Certificate of occupancy. Issuance by the governing building department is objective, dated, and hard to argue with. It can also lag the actual readiness of the building by weeks.
- Architect’s certification. The design professional signs that the work is sufficiently complete for its intended use. Independent, but only as fast as the architect’s site visit calendar.
- Owner’s beneficial occupancy. The date the owner begins using the space. Fits reality, but invites fights over whether partial use counts.
- A defined completion percentage. A fixed threshold tied to the schedule of values. Clean on paper, awkward when the final remaining work is HVAC commissioning.
A good construction contract picks one and sticks with it.
The Punch List as Scorecard Versus the Punch List as Hostage
Used well, the punch list is a scorecard. The architect walks the project, the contractor prepares a list of items to be completed or corrected, and the parties sign a certificate that records the date, the open items, and a deadline. The AIA G704 exists precisely to make that process orderly: the contractor drafts the list, the architect verifies and amends it, and owner, architect, and contractor all sign.
Used badly, the same list becomes a hostage. Items get added weeks after the walkthrough. Scope creep gets relabeled as punch work. A fresh list arrives the day retainage was supposed to be released.
Both patterns are common enough that neither side gets the benefit of the doubt without documentation.
What Each Side Should Actually Do Before It Becomes Litigation
The practical moves split cleanly by role. Neither side helps itself by waiting for the other to blink.
- For the contractor. Request the walkthrough in writing, with a date, and photograph completed work the day it’s finished. Prepare the punch list yourself before the owner does. If the owner occupies, send a dated notice that use has begun. Silence here is expensive later.
- For the owner. Walk the project with the architect, not alone, and separate code and functional items from cosmetic ones on the list itself. If you occupy before signing, say in writing why, and what remains open. Don’t add items a month later without flagging them as new.
- For both. Sign something. A certificate with an attached, dated punch list and a deadline protects everyone, even when the parties disagree about particular items. An unsigned project is a project where every clock stays frozen and every argument stays live.
Substantial completion disputes often come down to how clearly the contract defines completion and how thoroughly both parties document the remaining work. By establishing clear expectations, maintaining accurate punch lists, and addressing disagreements early, owners and contractors can reduce payment delays and avoid costly construction litigation.

How to Tell Whether a Property Is Actually Worth Its Asking Price

How to Encourage Your Child to Make Friends Without Forcing Social Situations

The Warning Signs Your Cat Might Be Seriously Unwell

Why Modern Cars Sometimes Need More Than Basic Repairs After an Accident

Why Taking Time for Yourself Can Feel Difficult and How to Make It Easier

Why Additional Insured Endorsements Matter Long After Construction Ends

How Much Time Do Household Chores Take, and How Can You Get It Back?

How Punch Lists and Substantial Completion Affect Construction Payment Disputes

Did You Know Your AC Is Working Harder in October Than August?

Why “One Less Thing to Think About” Is an Underrated Luxury

Top Ways to Ask for Help

How Can Split-Dollar Plans Help Businesses Retain Key Employees?

The Environmental Case for Upgrading Your Home’s Water Infrastructure

Tips for Working in a Small Local Government—And Actually Making It Work

How to Plan Your Best Trip to Russia: 5 Easy Steps

Why “Gymtimidation” Is Sabotaging Your Wellness Goals

World Cup Match Days Turn Into Daily Fan Rituals

The Floor Under the Cloud: Why Data Centers Still Rely on What You Can’t See

Career Pivots That Pay: Blue-Collar Skills Worth Learning in 2026 When Office Jobs Feel Shaky

The Power of Remembrance: Keeping Memories Alive
 Entertainment11 months ago
Casino Bonuses in Latvia: Comparing Offers and Tips for Beginners
 LifeStyle11 months ago
Why Support Systems Matter More Than We Admit During Hard Times
 LifeStyle10 months ago
Should You Buy or Build Your Next Home? Here’s How to Decide (Without Losing Sleep Over It)
 Health11 months ago
The Support Systems That Keep Independent Practices Competitive
 Finance12 months ago
How to Actually Protect Your Money with Smart Financial Moves

 Business12 months ago
How to Effectively Run a Completely Online Business

 Work11 months ago
Failed An Employment Background Check? Here’s How To Move Forward

 Finance11 months ago
The Generational Shift in How People Buy and Sell Cars Today