Finance
How to Quickly Open a Savings Account Online?

In today’s digital age, managing your finances has become less challenging. One way to start your financial journey is by opening a Savings Account online. It is a simple process that offers convenience and flexibility. This article lists the steps of opening a Savings Account online.
Choose the right bank
The first step to opening a Savings Account is selecting the right bank or financial institution. You should consider factors like the bank’s reputation, customer service, and the interest rates they offer. Many well-known banks, as well as online-only banks, provide online account opening services.
Gather your documents
To open a savings account online, you must provide personal information and documents. Be prepared to submit documents like personal identification, address proof, Social Security Number (SSN), and Tax Identification Number (TIN).
Choose the type of Savings Account
Banks offer a variety of savings accounts, each with its features, benefits, and savings account interest rates. You should choose the one that suits your needs. Common types include Regular Savings Accounts, High-Yield Savings Accounts and Certificates of Deposit (CDs).
Complete the online application
With all the necessary information, visit the bank’s website or Banking app and locate the “Open Savings Account” or “Apply Now” button. You will get directed to an online application form. Fill in the required fields with accurate information.
Funding your account
After completing the application, you must fund your new Savings Account. Most banks offer various options for making an initial deposit, such as –
- Transferring funds from an existing Bank Account: You can link your Savings Account to your current bank and transfer money electronically.
- Depositing a cheque: Some banks allow you to mail a cheque to fund your account.
- Direct deposit: If you have a source of income, like a paycheque, you can set up direct deposit into your Savings Account.
Review and confirm
Before finalising your application, review all the information provided for accuracy. Ensure your personal details, account type, and funding sources are correct. Once satisfied, you can proceed with the online savings account opening.
Verification and approval
The bank will review your application, verify your information, and run a credit check if necessary. Depending on the bank’s policies, this process can take a few minutes to a few business days.
Access your account
After your application approval, you will get a notification or e-mail with your account details, such as your account number and login credentials for online banking. After completing the process, you can manage and access your Savings Account from your home.
Conclusion
Opening a savings account online is a straightforward process that provides a secure place to save money and earn interest. It is a convenient way to take control of your finances and start building your financial future. So, follow these easy steps and be on your way to achieving your savings goals.

A framing sub wraps up a mixed-use building in year one, cashes the final check, and moves on to the next job. Eight years later, a tenant trips on a slab that cracked where the sub’s crew tied two pours together, breaks a hip, and sues the owner and the general.
The general tenders the claim back to the sub as an additional insured. The sub’s broker digs out the old certificate, sees the only endorsement on file was a CG 20 10, and figures out the policy that was supposed to protect them stopped responding the day the work ended.
Most completed-operations fights start right there, in the space between what a contractor thinks they bought and what the policy actually does when the phone rings. By then the project is closed, the paperwork is cold, and the people who negotiated the contract have moved on.
Stage One: The Contract Promises More Than the Endorsement Delivers
Most construction contracts require the contractor to name the owner, developer, and upstream contractor as additional insureds. The language usually reads something like “for ongoing and completed operations.” Fine on paper, but here’s the catch. The standard ongoing-operations endorsement, CG 20 10, was narrowed after 1985 so it stops responding once the work is finished. If that’s the only endorsement attached to the policy, the completed-operations half of the contract promise has nothing behind it.
Covering both halves generally takes two separate endorsements, as the Amwins client advisory on additional insured forms lays out: a CG 20 10 for the construction phase and a CG 20 37 for the years after the ribbon is cut. Plenty of contracts assume both are in place. Plenty of policies carry only one. A thoughtful business insurance program builds this handoff in, pairing the right additional insured forms with completed-operations limits that will still be meaningful a decade out.
Stage Two: The Latent Defect Shows Up
Water intrusion. Foundation movement. Failed waterproofing, EIFS problems, slab cracks.
Construction defects can also stem from decisions made long before a project is finished. As Emoovio explains in its article on construction preparation mistakes, rushed preparation can lead to premature failures that only become apparent months or years later.
These rarely surface in year one. Claims typically aren’t reported for a number of years, often up to ten, after a home is completed. Commercial projects follow a similar curve. By the time the damage is visible, the original crew is on different jobs and the insurance file is buried in deep storage.
State statutes of repose cap how far back a plaintiff can reach, but the ceilings are generous and they vary widely by jurisdiction. The practical window a contractor should plan to defend against runs well past a decade in many places.
Stage Three: The Tender Lands on the Wrong Policy Year
When the suit arrives, the general or the owner tenders it to every sub whose scope touched the alleged defect. Whether that tender gets accepted depends on four things, and none of them are what the current broker is quoting:
- The endorsement in force then. The policy that responds is the one on the risk when the property damage happened, not the policy in force today. A CG 20 10 on that old policy will usually fail to pick up a completed-operations claim.
- The schedule of insureds. Older endorsements often required the additional insured to be named specifically. If the upstream party isn’t on the schedule, or isn’t captured by a blanket clause tied to a written contract, the tender gets denied.
- The completed-operations limit. Products-completed operations usually has its own aggregate. If prior claims already chewed through it, there may be little or nothing left for this one.
- The surviving paperwork. No contract on file, no certificate, no endorsement copy, no coverage argument. Document retention for a contractor is a coverage issue, not a records issue.
Stage Four: Close the Loop Before the Next Project Starts
The fix is boring, and it works. Read the insurance exhibit in every contract before signing and match the endorsements on the policy to what the contract actually requires. If the contract calls for completed-operations additional insured status, confirm a CG 20 37 (or equivalent) is attached, not a CG 20 10 by itself.
Ask the carrier for a specimen copy of the endorsement, not a certificate. A certificate is a summary, not coverage. A few habits save real money later:
- Keep a project-by-project file. Store the signed contract, the certificate, and the actual endorsement forms together, by project, for at least the length of the longest statute of repose you work under.
- Watch the completed-operations limit. Buy it high enough that one bad project doesn’t exhaust it for everything else, and track erosion as claims come in.
- Keep tail coverage alive. If you change carriers, retire, or sell the business, confirm how completed-operations claims from prior years will be defended. Leave that question open and personal assets start getting discussed.
- Push back on blanket language that doesn’t match. If a contract demands coverage your policy doesn’t grant, flag it before signing, not after a tender.
Contractors who get surprised by a tender ten years out usually did the work well. What tripped them was an endorsement that expired the moment the job did.
Choosing a real estate agent can feel straightforward until you actually start meeting them. One agent suggests a higher asking price, another promises an aggressive marketing campaign, and someone else has a commission structure that looks considerably cheaper. Suddenly, comparing them isn’t so simple.
The best approach is to look beyond the sales pitch and ask questions that reveal how each agent actually intends to sell your property.
Whether you’re comparing several local agents or searching online for something like the best real estate agency Campbelltown has to offer, you want to understand the reasoning behind their recommendations rather than choosing someone based on one impressive number.
Before signing an agreement, these seven questions can help you work out whether an agent’s strategy, experience and communication style are right for you.
1. How Did You Arrive at Your Suggested Price?
It’s flattering when an agent gives you a higher estimate than everyone else, but that doesn’t automatically mean your home will sell for more.
Ask them to explain how they reached their figure. They should be able to discuss comparable properties, recent local sales, current competition and features that could increase or reduce your home’s appeal.
Pay attention to the evidence rather than simply choosing the highest valuation.
An unrealistic starting price can sometimes result in a property sitting on the market longer than necessary, so you want an agent who can justify their recommendation.
2. What Would You Do Before Putting My Home on the Market?
A good selling strategy can begin well before the first buyer walks through the door.
Ask what, if anything, the agent recommends changing before listing. You might hear suggestions involving decluttering, cleaning, minor repairs, landscaping, styling or professional photography.
More importantly, ask which improvements are actually worth spending money on.
You don’t necessarily need to renovate your home before selling it. A useful agent should help you distinguish between changes that may improve presentation and expensive projects that are unlikely to provide enough benefit to justify the effort.
Exterior problems should not be overlooked either, and homeowners who notice damaged tiles, leaks or other visible roof issues may want to speak with experienced roofers Nuneaton before putting the property on the market.
Before putting a property on the market, homeowners may benefit from professional clearance services offered by companies such as Triple A Removals, helping remove unwanted furniture and household items to make rooms appear more spacious and appealing to potential buyers.
3. How Will You Market the Property?
“Online marketing” isn’t much of an answer.
Ask exactly what the campaign includes. Find out where the property will be advertised, what photography and video will be used, whether social media forms part of the strategy and how the agent intends to reach buyers already in their database.
You should also ask what’s included in the agent’s fee and what you’ll pay for separately.
The goal isn’t necessarily to choose the biggest marketing package. It’s to understand how each element is expected to help reach suitable buyers.
4. Who Will Actually Handle My Sale?
At larger agencies, the person who wins your listing may not be the person you deal with every day.
That’s not automatically a problem. Strong teams can work extremely well. You simply need to know who is responsible for what.
Ask who will conduct inspections, answer buyer enquiries, provide feedback and negotiate offers. Find out who you’ll contact when you have questions and how quickly you can generally expect a response.
Knowing this beforehand can prevent frustration later.
5. How Will You Keep Me Updated?
Selling a home involves periods where you’re waiting for feedback, offers or information about what buyers are thinking.
Agree on communication expectations early.
Will the agent call after every inspection? Will you receive a written weekly report? How will they communicate offers? What happens if buyer interest is weaker than expected?
There’s no single correct communication schedule. Some sellers want frequent updates, while others prefer a weekly summary. What’s important is that the agent’s approach matches yours.
6. What Happens If the Property Doesn’t Sell as Expected?
It’s easy to discuss strategy when everyone assumes the campaign will go perfectly. A more revealing question is what the agent would do if it doesn’t.
Ask how they evaluate a campaign that’s attracting inspections but no offers. What if online interest is low? At what point would they recommend changing the marketing, presentation or pricing strategy?
You want to hear a thoughtful process rather than an automatic answer that the price simply needs to come down.
7. What Will I Pay From Start to Finish?
Before signing anything, make sure you understand the complete cost of selling.
Ask for a clear breakdown covering the agent’s commission or fee structure, marketing expenses and any other charges you could reasonably encounter.
If there are optional extras, find out what they are and when you would be asked to approve them.
You should also understand the terms of the agency agreement, including its duration and what happens if you decide the arrangement isn’t working.
Choose the Agent, Not the Biggest Promise
Selling your home is a significant financial decision, so there’s nothing wrong with interviewing several agents before choosing one.
Listen carefully to how they answer your questions. Strong agents should be able to explain their recommendations in plain language, support their pricing advice with evidence and be clear about costs and communication.
You’re not simply looking for the person who predicts the highest sale price or charges the lowest fee. You’re choosing someone to guide the campaign, communicate with potential buyers and negotiate on your behalf.
A few thoughtful questions before you list can tell you far more about that ability than an impressive presentation alone.
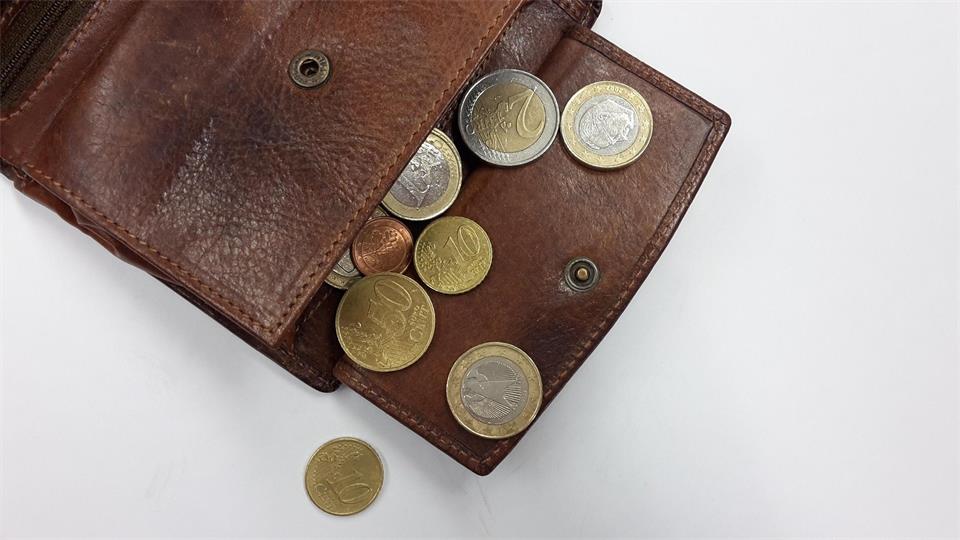
For much of modern history, personal finance was something people engaged with only occasionally, and in many cases reluctantly. Bills were paid, savings accounts existed quietly in the background, and financial planning often felt like a distant or specialised concern.
Today, this relationship with money is changing. Across generations, and especially among younger adults, people are thinking about finances more actively and more frequently. From budgeting apps to financial content on social media, money has become part of everyday conversation in a way which would have seemed unusual just a decade ago.
What’s driving this shift isn’t simply economic uncertainty, or technological change. It’s also a growing sense that financial awareness is an essential part of modern life.
Money is no longer a private topic
Not long ago, discussing money openly was considered uncomfortable, even a little impolite. Conversations about income, debt, and investing tended to take place behind closed doors. That social barrier has weakened considerably in the digital era.
Online communities, podcasts, and financial education channels have normalized discussions about budgeting, saving, and investing for the long term. People are sharing their financial journeys, successes, and lessons learned.
This openness has had an interesting effect. It has made money feel more understandable. When people hear others discussing the same questions, such as how to manage debt, start investing, and build savings, it becomes easier to view financial decision-making as a skill that can be learned, rather than an expertise reserved for experts.
Technology has changed our experience of money
The tools people use to manage their finances have also transformed dramatically. Mobile banking, automated budgeting tools, and accessible investment platforms have made financial management far more immediate and visible. Instead of waiting for a monthly bank statement, individuals can now see spending patterns in real time. Apps categorize purchases immediately, highlighting habits that may previously have gone unnoticed.
This constant visibility has shifted how people think about financial decisions. Rather than treat money management as a periodic task, many now see it as a regular, ongoing process. Something that can be gradually adjusted through small daily choices.
Confidence through understanding
Another important change is the growing emphasis on financial confidence. For many years, financial services have appeared complex or intimidating, filled with technical language and complicated options. More recently there has been a push across the financial sector to make information clearer and more accessible.
Entrepreneurs such as Alex Kleyner have increasingly argued that financial tools should serve people, helping them understand rather than overwhelming them with complexity.
This shift reflects a broader cultural change. People are not necessarily seeking perfect financial strategies; they are looking for the knowledge and confidence to make reasonable, informed choices over time.
As financial tools continue to evolve, this shift towards openness, understanding, and personal responsibility may prove just as influential as the technology itself. When individuals feel informed and confident about their finances, the conversation around money changes – from something avoided to something actively shaped.

Why Additional Insured Endorsements Matter Long After Construction Ends

How Much Time Do Household Chores Take, and How Can You Get It Back?

How Punch Lists and Substantial Completion Affect Construction Payment Disputes

Did You Know Your AC Is Working Harder in October Than August?

Why “One Less Thing to Think About” Is an Underrated Luxury

Why Football Fans Never Forget an Underdog Win

The Hidden Admin Load Reshaping Healthcare Burnout in 2026

The Cost of Deferred Maintenance: How Small Building Problems Become Big Business Expenses

The Cleaning Decisions That Shape Focus, Mood, and Sick Days at Work

The Sticky House Problem: Why Your AC Cools the Air but Leaves the Room Feeling Damp

So You’ve Got Multiple Offers for Your Business. Now What?

What Is the Construction Process Behind Modern Wind Power Plants?

Top Ways to Ask for Help

What Makes an Online Casino Safe Before You Even Play

How to Identify and Eliminate Efficiency Gaps in Complex Business Operations

How Do Recycling Facilities Use Shredders for Plastic Waste Processing?

How Can Split-Dollar Plans Help Businesses Retain Key Employees?

The Environmental Case for Upgrading Your Home’s Water Infrastructure

When Do You Need a Business Debt Settlement Partner?

Tips for Working in a Small Local Government—And Actually Making It Work
 Entertainment11 months ago
Casino Bonuses in Latvia: Comparing Offers and Tips for Beginners
 LifeStyle11 months ago
Why Support Systems Matter More Than We Admit During Hard Times
 LifeStyle9 months ago
Should You Buy or Build Your Next Home? Here’s How to Decide (Without Losing Sleep Over It)
 Work12 months ago
How to Create a Comfortable Environment for Your Team
 Health11 months ago
The Support Systems That Keep Independent Practices Competitive
 Finance11 months ago
How to Actually Protect Your Money with Smart Financial Moves
 Gifts12 months ago
Rose Bouquet Flower: timeless elegance for every occasion

 Business11 months ago
How to Effectively Run a Completely Online Business